#Superbonus Renovations 110%
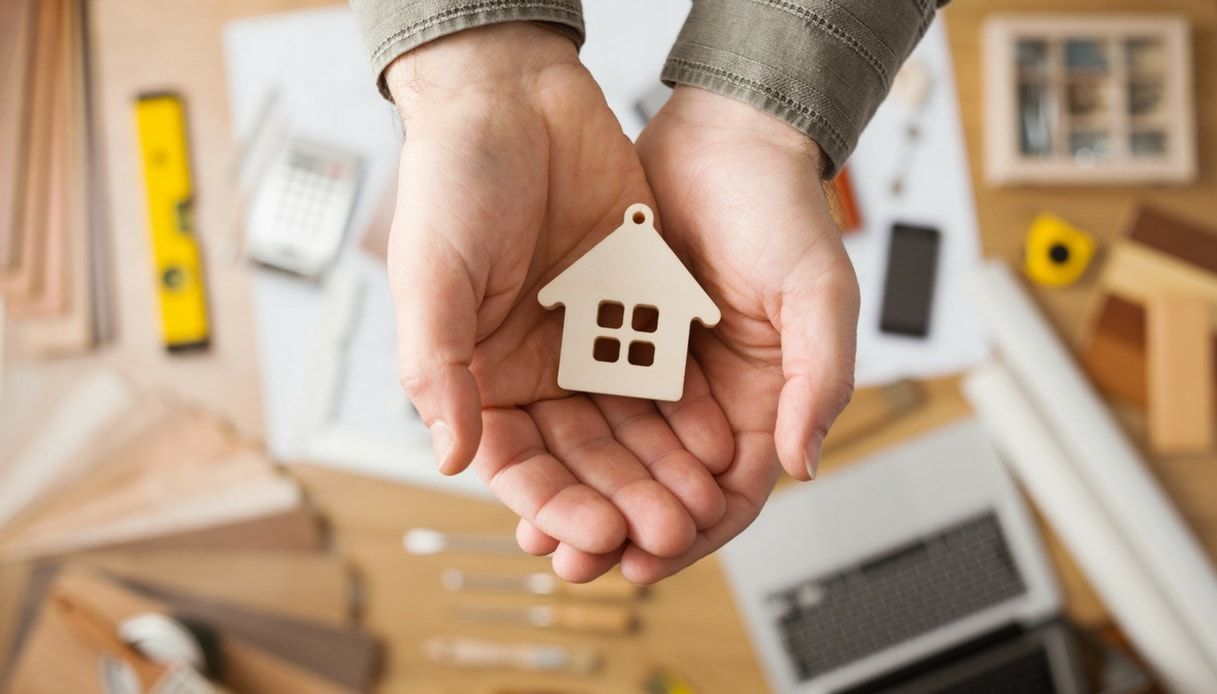
The 110% Superbonus for renovations also apply to non-residents
The 110% “superbonus” (provided for in Art. 119 of LD 34/2020) concerns all the taxpayers, residents and non-residents within the territory of the State who bear the expenses for energy and #redevelopment works.
Then taxpayers resident #abroad too may benefit from the deduction of 110% for specific interventions aimed at increasing the #energy efficiency of buildings, reduction of #seismic risk, for the #installation of #photovoltaic systems and columns for charging #electric vehicles, in the event of deduction of the expenses incurred between 1° July 2020 and 31° December 2021.
Instead of the deduction, the taxpayers can also opt for a contribution in the form of a discount in the invoice by the supplier, or as a transfer of the corresponding deduction to other subjects, including banks and other financial intermediaries (ex Art. 121 of LD 34/2020).